Utah short sale help for Herriman homeowners
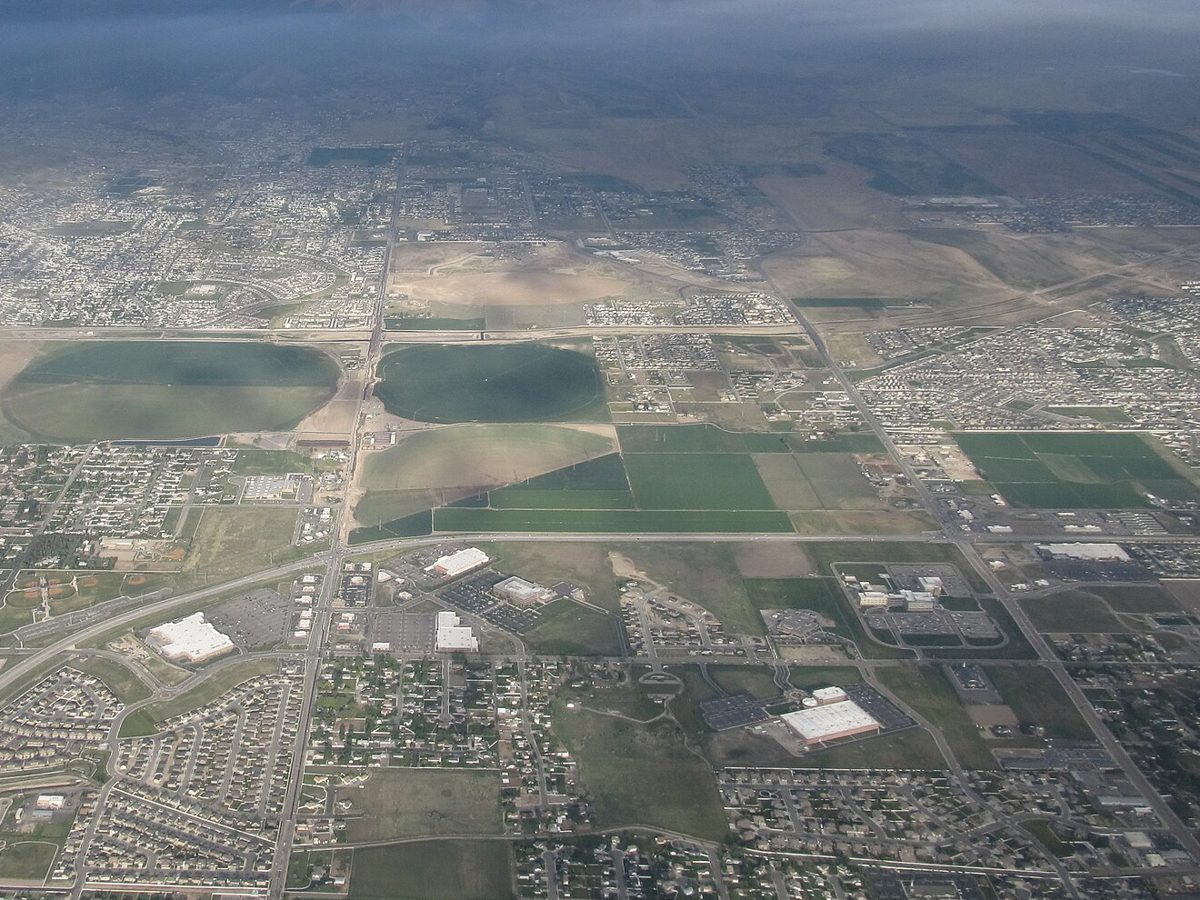

A Utah short sale is a sale of your home for less than you owe, approved by every lender on the loan, and it can replace a foreclosure if it closes before the trustee sale. Utah lenders usually foreclose outside court, and the trustee must wait at least three months after recording a notice of default before giving notice of sale. Herriman's typical home value was $601,499 in August 2026, below its August 2022 level, according to Zillow.
Our recommended agent
Abril Burgoyne, PAK Home Realty, Murray. She lists Herriman among her service areas and works in English and Spanish.
Where are you now?
Behind on payments
A loan modification, forbearance or a short sale may stop a Utah foreclosure, but each has to happen before the trustee sale.
Owe more than the home is worth
You can still sell. If the price will not cover the loan, the lender has to approve a sale for less than you owe.
Received a notice of default
The notice of default starts the foreclosure timeline. See each notice and deadline, and how long a short sale takes.
Want to understand short sales first
How a short sale works, who has to approve it, and what it means for your credit and taxes.
Request a confidential review
Tell us where things stand with your mortgage. We pass your request to our recommended agent, who will call you back to talk through your options, including whether a short sale fits.
Your request goes to Abril Burgoyne, our recommended agent. It stays confidential, and there's no obligation to list.
Guides
Short sale guides
Utah foreclosure
Selling in Herriman
Herriman home values
Zillow Home Value Index (typical home value, mid-tier), August 2026, from Zillow Research; 30-year rate from the Freddie Mac Primary Mortgage Market Survey, week of October 8, 2026.
What is a short sale?
A short sale is an ordinary listed sale with one extra approval. The buyer's price is less than the payoff on your mortgage, so the lender has to agree to take the sale proceeds and release its lien. If there is a second mortgage, a HELOC or an HOA lien, each holder has to agree to its share too. Our explainer on how a short sale works and who approves it covers why lenders say yes and what they ask for.
The work happens in a set order: price the home on recent sales, sign a buyer, send the lender a package with a hardship letter and financial records, wait for the lender's valuation and decision, then close on the date in the approval letter. The step-by-step short sale timeline walks through each stage, including the approval letter you should read before you sign anything.
A short sale is one of several ways out. If the home is worth more than you owe after selling costs, a normal sale is simpler, and our page on selling a Herriman home when money is tight compares a listed sale, a short sale and a cash buyer side by side.
Who does a short sale fit in Herriman?
Zillow's typical home value for the City of Herriman was $601,499 in August 2026, up 0.8% from a year earlier but still below the $614,921 Zillow recorded for August 2022. Owners who bought or refinanced near that 2022 level with a small down payment can owe close to, or more than, what the home would sell for today. Figures for ZIP 84096, which also covers areas outside Herriman, follow the same pattern.
Owners who bought near the 2022 high
Example: a Herriman home worth $601,499 with a loan balance of $620,000. A sale at that value leaves the loan about $18,500 short before any selling costs, so the lender would have to approve the sale for less than the payoff. Our page on owing more than your home is worth shows how to run this check with your own numbers.
Owners with a second mortgage or HELOC
A first loan that the sale price covers can still leave a second lien unpaid. The second-lien holder has to release its lien before the title can transfer, so a sale that looks fine on the first loan can still need short sale approval from the second.
Owners who are behind on payments
A short sale does not require you to be behind. Fannie Mae and Freddie Mac consider borrowers who are current or delinquent. If you have missed payments, the date of any notice of default matters, because the sale has to close before the trustee sale. Our page on the pre-foreclosure stage in Utah explains what happens between the first missed payment and that notice.
How does foreclosure work in Utah?
Most Utah home loans are secured by a trust deed, and the lender usually forecloses through a trustee sale without going to court. Federal rules generally bar the servicer from recording the first foreclosure notice until the loan is more than 120 days delinquent. The full sequence, with each statute, is in our guide to Utah trust deed foreclosure.
Notice of default
The trustee starts the process by recording a notice of default with the county recorder; for Herriman homes that is the Salt Lake County Recorder. Utah Code 57-1-24 requires at least three months between that recording and the notice of sale. Within three months of the notice of default, Utah Code 57-1-31 lets you reinstate the loan by paying the past-due amount plus costs and fees.
Notice of trustee sale
The notice of sale must be published once a week for three consecutive weeks and posted on the property and at the county recorder's office at least 20 days before the sale. A trustee can postpone the sale; a postponement longer than 45 days past the original date requires a new notice.
Trustee sale and after
The sale is a public auction, and the lender can bid the debt it is owed. There is no right of redemption after a Utah trustee sale. The lender then has three months to sue for any deficiency, and the court caps the judgment at the debt minus the home's fair market value on the sale date.
What are your options if you can't keep the home?
Each option has its own approval, deadline and effect on credit. The table below is a summary; our page on every way to stop a Utah foreclosure covers each one in depth.
| Option | Who decides | Utah deadline to watch |
|---|---|---|
| Reinstatement | Your right by statute if you pay the amount due | Within three months of the notice of default (57-1-31) |
| Loan modification or forbearance | Your servicer | A complete application more than 37 days before a sale gets federal sale protection |
| Listed sale with equity | You and your buyer | Close before the trustee sale |
| Short sale | You, your buyer and every lien holder | Close before the trustee sale |
| Deed in lieu | Your lender | Usually after a short sale attempt |
| Foreclosure | The trustee | No redemption after the sale (57-1-28) |
Keep the home
Reinstatement, a repayment plan, a loan modification or forbearance keep you in the home if your income can support the payment. If you send your servicer a complete loss mitigation application more than 37 days before a scheduled sale, federal rules stop the servicer from holding the sale until the application is resolved.
Sell the home
A listed sale works when the price covers every lien and the costs of selling. A short sale works when it doesn't, and the lenders agree. The comparison of a short sale and a foreclosure sets out credit reporting, deficiency and timing for each.
Give the home back
A deed in lieu transfers the home to the lender in exchange for a release. FHA, for example, requires the borrower to have tried a short sale first. Our page on a short sale or a deed in lieu compares the two.
How does the confidential short sale review work?
The review is a conversation about your numbers and your dates, with no obligation to list. It goes to our recommended Herriman short sale agent, who reads what you send and calls or writes back.
- What to have ready: your lender's name, your loan balance and any second mortgage, HELOC or HOA balance, your monthly payment, how far behind you are, and the date on any notice of default or notice of sale.
- What the review covers: a value range based on recent sales near you, whether a normal sale could cover your liens, which options apply to your loan type, and the deadline the Utah foreclosure timeline sets.
- What it is not: a promise of lender approval, a stopped foreclosure or a waived deficiency. Only your lender can approve a short sale.
Before you pay anyone for foreclosure help, talk to a HUD-approved housing counselor. The CFPB's housing counselor tool searches HUD's list by ZIP code.
Which areas does this site cover?
Herriman first, and Utah as a whole. The Utah statutes on trust deed foreclosure and short sale deficiencies apply statewide, so the guides apply to a home in Salt Lake County or anywhere else in the state. Local details, such as the county recorder, property tax dates and HOA liens, are written for Herriman and Salt Lake County.
Herriman's ZIP code, 84096, is not the same as the city limits. Census data shows that only about 28% of the ZIP's land is in Herriman; most of the rest is unincorporated, part is in Riverton, and a small part of Herriman lies in 84065. Our Herriman home values and HOA guide uses the city figure first for that reason.
This site explains how short sales and foreclosure work; it is not legal, tax or financial advice. Before you rely on any deadline, confirm your dates with a Utah attorney or a HUD-approved housing counselor, and ask a tax professional about any forgiven debt.
Short sale questions
How long can a short sale last?
There is no fixed length. The sale needs a buyer, a complete lender package, the lender's own valuation and a written approval before closing. Federal rules require a servicer to answer a complete loss mitigation application within 30 days if it arrives more than 37 days before a sale. FHA gives an approved seller four months to find a buyer. A Utah short sale has to close before the trustee sale date.
Can you do a short sale in Utah if you are current on your mortgage?
Yes, for many loans. Fannie Mae and Freddie Mac consider short sales for borrowers who are current or behind, though the lender still needs a hardship and a price close to market value. FHA's standard short sale requires the borrower to be at least 61 days behind. Ask your servicer which investor owns your loan, because the rules differ.
Can a Utah lender sue me after a short sale?
Utah Code 78B-2-313 bars a lender from suing for the shortfall after a short sale of a single-family home unless the suit is filed within three months after the release or reconveyance is recorded. The bar does not apply if there was fraud or if you signed an agreement to pay some or all of the deficiency. Read the approval letter carefully and confirm with a Utah attorney.
Will a short sale stop a trustee sale in Utah?
Only if it closes first. A short sale replaces a foreclosure when the lender approves it and the sale records before the trustee sale. A trustee can postpone a sale, but nothing requires it. A complete loss mitigation application sent more than 37 days before the sale date gives federal protection while it is reviewed.
Is a short sale better than foreclosure in Utah?
It often costs less in practice, though not always on a credit score. FICO's research found no significant score difference between a short sale and a foreclosure, but loan waiting periods are usually shorter after a short sale, and Utah's three-month short sale deficiency deadline applies. Our comparison page sets out each difference.
Do I need a lawyer for a short sale in Utah?
Not always. Freddie Mac, for example, requires the home to be listed with a licensed agent on the MLS, and that agent works with the lender on the sale. A Utah attorney is worth consulting if a trustee sale is close, if the approval letter does not waive the deficiency, or if you are considering bankruptcy. The Utah State Bar's LicensedLawyer.org directory lists attorneys.
Does this site list short sale homes for sale?
No. Herriman Short Sale explains how short sales and foreclosure work for owners in Herriman and across Utah. Buyers can read our guide to buying a short sale, which covers offers, lender approval and the wait for an answer.
Behind on payments in Herriman?
Talk to Abril about whether a short sale fits your situation.